Debt Capital Advisors · Credit Review1 of 9 · Overview
Investor-side credit review

Read the debt.
Understand the risk.

Independent review and analysis of credit products for private debt investors, family offices and smaller funds without full-time legal or credit teams.

More than 60 years of combined Wall Street legal and banking experience.

Discuss a potential review

Focused on the terms, cash flows and downside paths that shape the investment.

Capital structureIllustrative review lens
Senior securedCollateral, priority, covenants
Senior unsecuredGuarantees, baskets, payment rights
Convertible / structuredOptionality, triggers, cash-flow waterfall
Junior capitalSubordination and recovery position
Terms interact across instruments. The review considers the position held and the documents that govern it.
Syndicated facilitiesHigh-yield notesConvertible notesStructured productsJunior capital
Why the smaller investor should look closer

Credit is growing. The questions are getting sharper.

Market-level trends do not predict a loss on any one deal. They do make liquidity, valuation, borrower cash flow and creditor rights worth testing before an investor commits.

01

Liquidity can be conditional

The Fed reported increased redemption requests at semi-liquid private credit funds in Q1 2026; most managers capped redemptions. Requests remained manageable, but access depended on fund terms.

Ask: What are the notice periods, caps, gates and suspension rights?
02

Private-credit valuations need a method

Privately negotiated loans do not trade like public bonds. In October 2026, the Fed added private credit vehicles and loans to the Financial Accounts after noting that much of this activity had not been separately identified there.

Ask: How are asset and recovery values marked, and what data support them?
03

Borrower stress can change the deal

In its May 2026 survey of market contacts, the Fed reported more concern about private credit, including redemption pressure, weaker sentiment and AI-related disruption to some borrowers.

Ask: Can cash flow cover interest, and who can amend, extend or prime my position?

Sources: Federal Reserve, October 16, 2026; Financial Stability Report, May 2026; Near-Term Risks, May 2026.

Impaired debt · Distressed situations

When the story breaks, the documents decide what is left.

“Senior,” “secured,” “investment grade” and “AAA” describe different parts of a risk picture. They do not, on their own, guarantee liquidity, stable value, uncontested collateral or a particular recovery.

Collateral · Receivables

First Brands: asset claims can be disputed

The DOJ’s January 2026 indictment alleges fake or duplicated invoices, concealed inventory financing and misleading financial statements; those are allegations, not findings. Separately, a factoring lender’s asserted first-lien claim to about $60.5 million of receivables was disputed in court, and the dispute was remanded for further proceedings.

Investor test: Verify invoice-level collateral, cash control, duplicate liens, related-party flows and the actual priority of the claim.
Priority · Amendments

Serta Simmons: a first lien can be reprioritized

A group of lenders participated in a 2020 “uptier” exchange while others were excluded. The Fifth Circuit held that the transaction did not qualify as an “open market purchase” under that agreement, reversed the bankruptcy court’s ruling and remanded contract claims.

Investor test: Read the actual pro rata sharing, sacred-rights, open-market-purchase and amendment provisions; identify who can consent and who can be left behind.
Ratings · Market value

AAA mortgage securities: rating is not a price floor

In a 2009 release, the SEC cited a 70% decline in the value of AAA-rated mortgage-backed securities from January 2007 to January 2008. That was a market-value decline in the cited category, not a claim that every AAA security defaulted or lost 70% of principal.

Investor test: What does the rating cover? Which market, liquidity, prepayment, structure and scenario risks sit outside it?
Potential opportunity · Not a recommendation

Distress can create a price gap—but only if the recovery thesis survives scrutiny.

Investors may evaluate discounted claims, rescue capital or a restructuring exchange when the entry price, priority and expected recovery justify the risk. The diligence has to account for cash burn, collateral value, competing liens, new-money priority, dilution, legal disputes, holding period and exit path.

What DCA can mapClaim and collateral positionPriority and amendment controlDownside waterfall and timingKey facts to verify before commitment

Sources are linked with each example. Court rulings are transaction-specific; the First Brands indictment contains allegations. Case studies are educational and do not predict the result of another investment.

Why independent review
The offering tells the investment story. The documents determine what happens when the story changes.

Private debt investors can encounter complex financing documents without the in-house legal and credit staff available to larger institutions. A focused review can help surface how economics, priority, covenants, optionality and remedies fit together before capital is committed.

Debt Capital Advisors brings a commercial credit lens together with financing-document experience. The work is designed to support an investor’s own diligence and decision process.

Products reviewed

Complex instruments.
Clearer questions.

Review scope follows the instrument, investor position and available materials. The analysis connects stated economics to rights and risks in the governing documents.

01

Syndicated debt facilities

Term loans, revolvers, covenant packages, collateral, guarantees and intercreditor arrangements.

02

High-yield notes

Indenture protections, debt and lien baskets, restricted payments and change-of-control terms.

03

Convertible notes

Conversion mechanics, dilution, ranking, events of default and issuer or holder options.

04

Structured products

Cash-flow priorities, triggers, collateral, waterfall mechanics and structural dependencies.

05

Junior capital

Payment subordination, standstill provisions, intercreditor rights and recovery position.

06

Special situations

Selected refinancings, exchanges and amendments where changes in terms may affect an investor’s position.

One investment, two lenses

Test the return case against the documents.

Analysis is most useful when the financial thesis and contractual position are considered together.

Credit and financial analysis

Examine the assumptions that support repayment and the return being offered.

  • Cash generation and debt-service capacity
  • Leverage, liquidity and maturity profile
  • Cash-pay and PIK economics, fees and optionality
  • Downside and refinancing scenarios

Financing-document analysis

Map the rights, protections and constraints that govern the investor’s position.

  • Ranking, collateral and guarantees
  • Covenants, baskets and amendment thresholds
  • Transfer, enforcement and default provisions
  • Intercreditor terms and recovery constraints
Review process

A defined path from documents to discussion.

Each engagement begins with a specific question and ends with an organized set of findings, open issues and risk/reward considerations.

01

Scope

Confirm the product, investor’s position, available materials and requested review.

02

Review

Read the economics and governing documents, including the relevant capital-structure context.

03

Test

Identify dependencies, downside scenarios, decision points and questions for the deal team.

04

Report

Deliver a concise memo and discuss key findings with the investor or investment team.

Scope and timing depend on document volume, transaction complexity and the information available.

The work product

A focused memo for the investment conversation.

The review is organized to help investors see where the return comes from, what rights they receive and which assumptions deserve a closer look.

  • Key economics and capital-structure position
  • Material rights, protections and limitations
  • Downside scenarios and recovery questions
  • Open diligence items for counsel, arranger or issuer
  • Risk/reward observations tied to the documents
Team

Wall Street finance experience, focused on the investor’s position.

DCA brings legal and banking perspectives together to connect the credit story to repayment, priority and recovery terms.

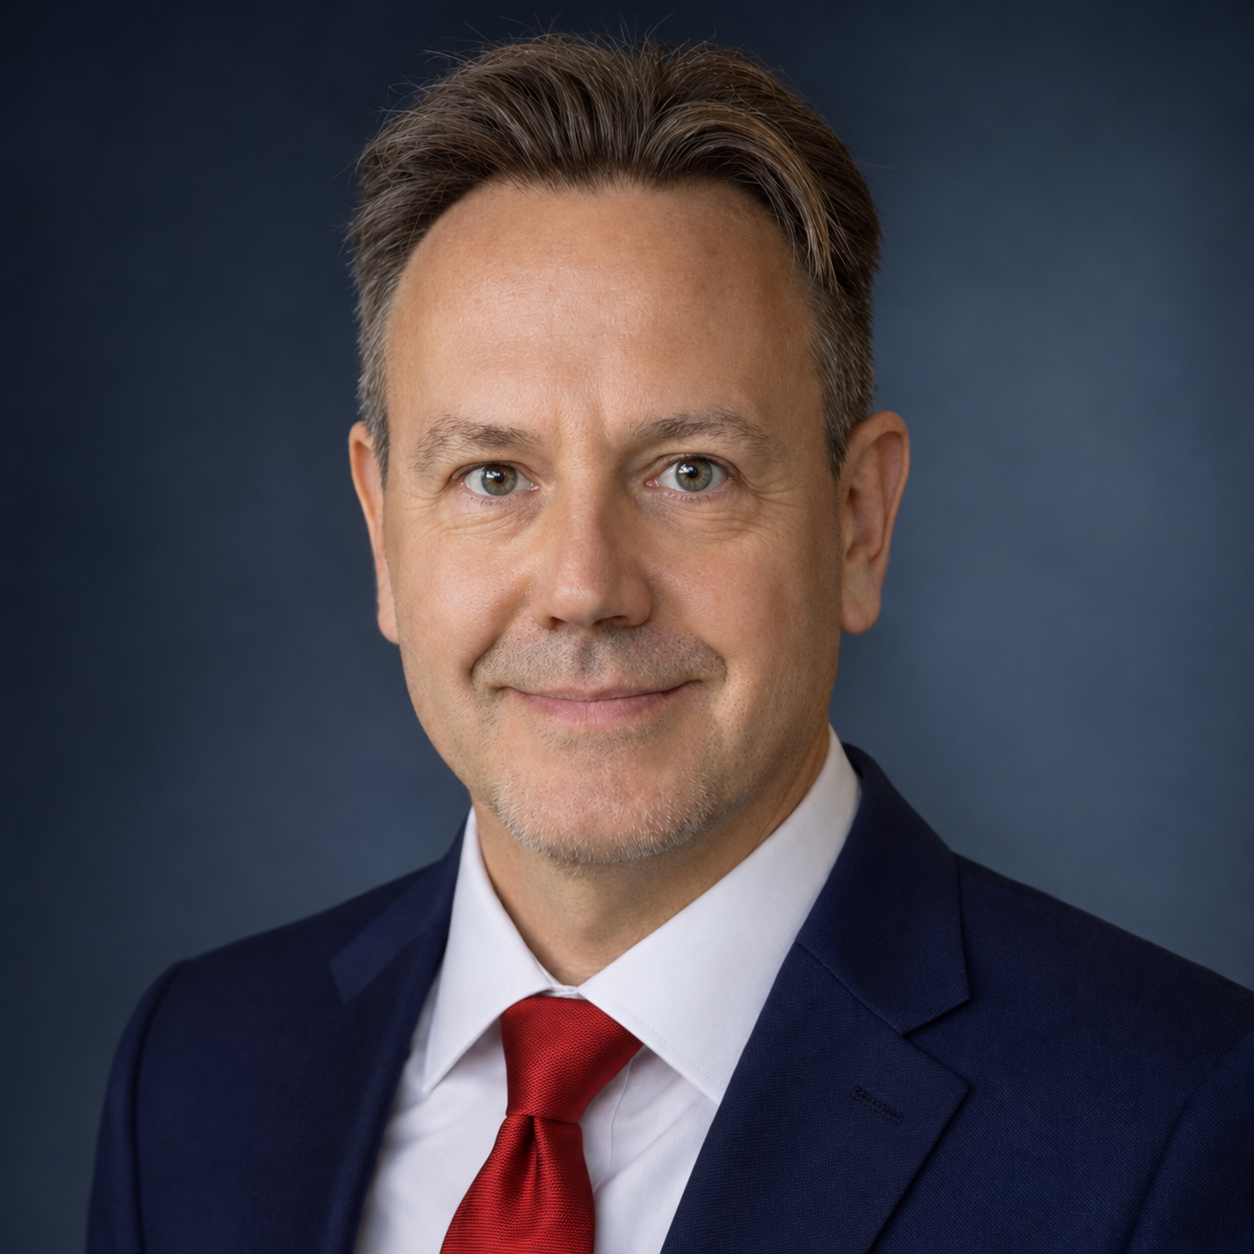
Michael Simon Baker, Managing Member of Debt Capital Advisors
Michael Simon BakerManaging Member
Team experience

DCA is a team of legal and banking professionals

The team brings more than 60 years of combined Wall Street finance experience to repayment analysis, financing terms, creditor priority and downside recovery.

Start a conversation

Have a credit opportunity that deserves a closer read?

Share the product type, your role in the transaction and the question you need the review to answer. Engagement scope can be discussed before materials are exchanged.

New York office
167 Madison Avenue, Suite 205
New York, NY 10016
Contact Debt Capital Advisors